What growing businesses need from a bank is remarkably consistent. They need direct access to bankers who understand their business, treasury management experts who can help improve cash flow and efficiency, and local decision-makers who can move financing requests forward. That combination comes from how a bank is structured and who is empowered to serve clients, not from how many branches it operates.
For decades, many banks competed by building larger branch networks. Today, banking models are evolving in different ways. Some institutions are buying other banks, others continue opening branches to attract consumer deposits, while others focus on technology, specialized expertise, and relationship-based service that businesses need. At First Business Bank, that relationship-focused model has contributed to a 97% client satisfaction rating and a Net Promoter Score of 78, significantly exceeding industry benchmarks.
What Businesses Really Need From Their Bank
Most business owners don't visit a bank branch every week or even every month. They deposit checks remotely, initiate payments electronically, monitor account activity online, and work directly with bankers by phone, video conference, or in person at their business.
As banking technology has advanced, convenience has become less about proximity and more about accessibility. A business owner may never need a branch around the corner, but they do need quick answers, responsive service, and access to financial specialists who understand their goals.
When evaluating a banking relationship, questions such as these often matter more than branch density:
Can I Quickly Reach the Right Person When I Need Help?
When issues arise, businesses need direct access to experienced professionals who can provide answers and resolve problems efficiently. Waiting for a call center transfer or navigating multiple layers of contacts can create unnecessary delays when time-sensitive decisions need to be made.
Does My Banker Understand My Industry and Business Model?
Every industry has unique challenges and opportunities. A manufacturer may need guidance on equipment financing and working capital. A professional services firm may have different cash flow needs than a distributor or healthcare practice. Bankers who understand an industry's financial realities can often provide more relevant recommendations and solutions. See how industry experience at your bank matters.
Can Treasury Management Solutions Improve Efficiency and Cash Flow?
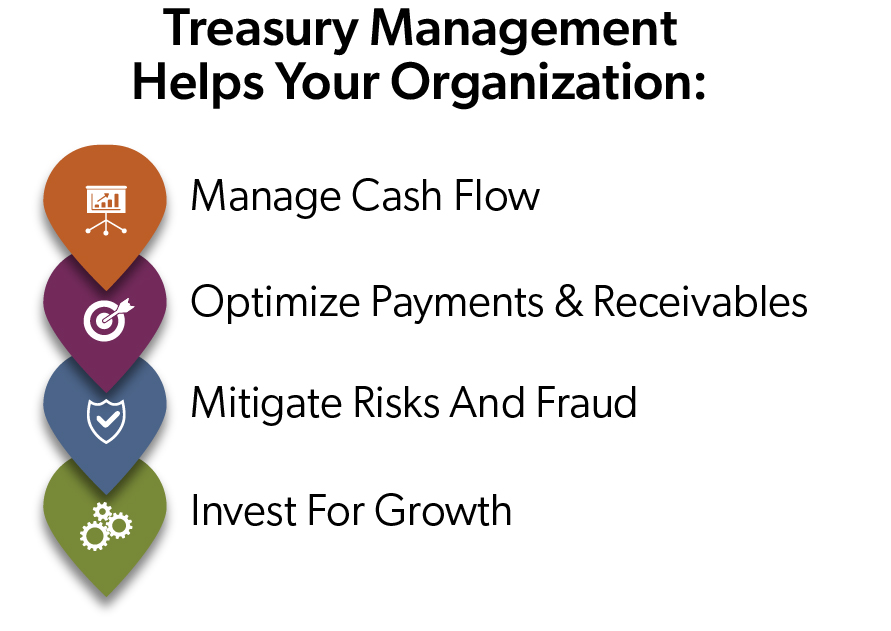 Treasury management has become an increasingly important component of business banking. Solutions such as fraud prevention tools, digital payments, automated receivables, account reporting, and liquidity management can help companies gain greater control over cash flow while reducing administrative burden.
For many businesses, the value extends beyond technology. Experienced treasury management professionals can help identify opportunities to streamline receivables, optimize payables, strengthen fraud controls, and improve liquidity. As business needs become more complex, access to knowledgeable specialists can be more valuable than access to additional branch locations.
Are Lending Decisions Made Locally?
When opportunities emerge, business leaders often need answers quickly. Access to local decision-makers can help streamline the lending process and provide greater confidence that the individuals evaluating a request understand the local market and the business behind the numbers.
Does The Bank Have Specialists Who Can Support Changing Business Needs?
As businesses grow, their financial needs often become more complex. Access to treasury management professionals, commercial lenders, wealth advisors, and other specialists can help ensure the banking relationship continues to support the organization's goals over time.
These factors often have a greater impact on a business's day-to-day operations and long-term success than the number of locations on a map.
Does The Bank Open Doors For My Business?
A bank's value can extend beyond its products and services. Bankers who are active in their industries and communities often connect clients to potential partners, customers, and advisors. A commercial banker might introduce a manufacturing client to a supplier facing capacity constraints elsewhere or connect a growing company with an accountant or attorney who specializes in their industry. That kind of connection depends on bankers who stay genuinely engaged in the local business community they serve.
Bank Branch Networks Continue to Evolve
Banking markets across Wisconsin and Kansas City have changed significantly over the past decade.
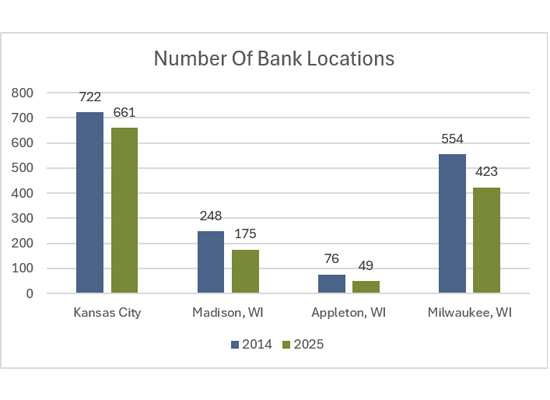 Between 2014 and 2025:
- Banking locations declined from 554 to 423 in the Milwaukee MSA, a 24% decrease.
- Banking locations declined from 248 to 175 in the Madison MSA, a 29% decrease.
- Banking locations declined from 76 to 49 in the Appleton MSA, a 36% decrease.
- Banking locations declined from 722 to 661 in the Kansas City MSA, an 8% decrease.
At the same time, some large national banks continue opening new branches in selected markets to grow consumer deposits. The result is a banking industry where institutions are pursuing different strategies based on the clients they serve.
For businesses, however, one thing remains consistent: access to expertise, technology, and responsive service often matters more than branch count. The more important question is how a bank chooses to invest its resources. Banks that prioritize experienced bankers, treasury management expertise, local decision-making, and technology often provide more value to businesses than a larger branch network.
Does Relationship Banking Deliver Better Results?
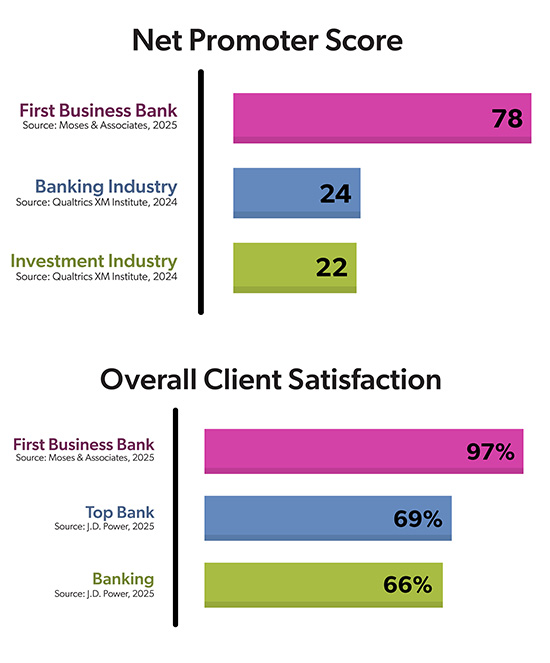 A banking model built around expertise, accessibility, and relationships only matters if clients find value in it. First Business Bank regularly measures client satisfaction through independent research. In 2025, First Business Bank achieved:
- 97% overall client satisfaction
- A Net Promoter Score (NPS) of 78
Those scores significantly outperform banking industry benchmarks and reflect what commercial clients consistently value most: responsive service, knowledgeable professionals, and trusted relationships. When businesses can work directly with experienced bankers and specialists who understand their goals, the result is often a stronger banking experience than branch access alone can provide.
Built Around Business Relationships Since Day One
Since 1990, First Business Bank has focused exclusively on helping businesses, business owners, executives, and high-net-worth individuals reach their financial goals. Rather than investing in a large retail branch network, the bank built specialized teams in commercial lending, treasury management, private wealth, specialty finance, and other areas that directly support client growth and financial success.
Updated: 9/21/2026